| Subscribe Read in Browser |
 |
| Today's newsletter is sponsored by |
 |
|
|
|
|
|
|
| Getting The Most Out Of Medicare: The Deadlines You Can’t Miss And The Decisions You Can’t Afford To Get Wrong |
Speaking of Medicare…if trying to make sense of it has ever left you more confused than when you started, you’re not alone. Between the parts, the plans and the deadlines, it’s easy to make a costly mistake without even realizing it.
On a special episode of the HerMoney Podcast, sponsored by LIMRA, Jean sat down with mother-daughter Medicare experts Diane Omdahl and Melinda Caughill of 65 Incorporated to break down exactly what you need to know – including how to choose between Original Medicare and Medicare Advantage.
As Omdahl puts it, the two paths are "night and day." "Part A, B, and D are basically set up and controlled by the government – you know what you're getting into. You pay a monthly premium; you have predictable out-of-pocket costs," she explains.
Medicare Advantage, on the other hand, is run by private insurers who set their own rules. It can look cheaper up front – but that savings comes with strings attached. "[You have] predictable care with Original Medicare, very few coverage rules…you don't deal with networks," adds Omdahl. "Then you get into Medicare Advantage and you have networks, you have prior authorizations and an unpredictable kind of cost."
For many, the decision comes down to risk tolerance and health – not just today’s health, but tomorrow’s. "At some point, our health changes from healthy to not so healthy or not healthy at all; you may not be able to change the type of coverage you have later in life," cautions Caughill.
🩺 MORE FROM OUR FRIENDS AT LIMRA: Your 5-Step Planning Guide To Healthcare In Retirement |
|
|
|
|
| The Book That Gets The Group Chat Going |
"Perhaps the best measure of a how-to book is whether it lights up the group text. The Forever Paycheck, by the veteran money journalist Jean Chatzky, got my siblings and me going by page 9," writes veteran New York Times journalist Ron Lieber (read his full take here).
That’s the kind of reaction The Forever Paycheck is getting. The practical, no-nonsense guide (which just hit the NYT bestseller list!) is a playbook for turning what you’ve saved for retirement into income you can actually count on, for as long as you need it.
Grab your copy here – and don’t be surprised if it inspires a group chat of your own! |
|
|
|
| This Week In Your Wallet |
 |
NOT so many happy returns. As The Wall Street Journal reports (and maybe as you’ve experienced), it’s getting a lot harder to return things you’ve purchased, with shoppers running into surprise fees, shorter return windows and delayed refunds. For example, 68% of retailers now charge a return fee at least some of the time – up from 43% five years ago – and refund windows have shrunk too (39 to 37 days overall, with bigger brands cutting theirs from 43 to 38). A good reminder to always read the fine print before hitting "add to cart."
Everyone is hustlin’. The share of Americans holding multiple jobs keeps climbing, but who’s doing so is shifting. Before the pandemic, low-income, middle-income and high-earners moonlighted in roughly equal numbers – but not anymore. According to the Richmond Fed, that has changed in the past few years: middle-income earners are much more likely to hold multiple jobs than their lower-earning counterparts, and they sit just barely below their higher-earning peers. "The second job is no longer just a survival tactic for the lowest earners, or a nice income boost for the highest earners — it's increasingly showing up for college-educated, middle-income Americans and the women of the workforce, who seem to be seeking out an extra buffer of stability and income," Business Insider reports. Are you a side hustler? Hit reply and tell us what you do! We’ll feature some of the best side hustle ideas in an upcoming newsletter.
The Fed just raised rates for the first time in over three years. Before you brush this off as another headline, it’s worth knowing what the quarter-point hike could mean for your money. The decision will quickly impact credit card borrowers, who will see an additional $1.38 a month in interest on the average $6,600 card balance. "The increase is small on its own, but can add to the burden for borrowers carrying larger balances month to month," the WSJ notes. In banking, the quarter-point increase should push savings rates higher, especially at online banks. So if you’ve been waiting to open a high-yield savings account, the coming days and weeks will likely be a good time to do so. |
|
|
|
| Things That Save You Money |
 |
| ● |
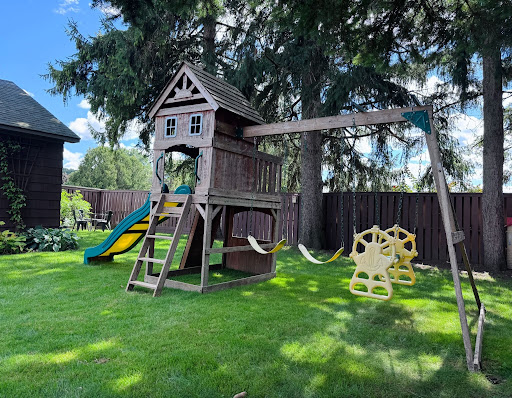
If you’ve been thinking about buying your kids (or grandkids) a brand new swingset…don’t. One quick look through Facebook Marketplace and you’ll likely find tons of secondhand options – often free, from people who just want their yard back. One HerMoney staffer scored the set above from a neighbor. $100 and an hour of pressure washing saved her family an estimated $1,000. |
| ● |
Buying a car? It pays (literally) to know which models hold their value – and which tank fastest. |
| ● |
If you’re shopping in-store at Target, consider this your reminder to ALWAYS compare online prices before checking out. One member of the HerMoney team was about to pay $190 in-store for a Casaluna comforter – a quick look at the Target app showed the same one for $160 online. She flagged it to an employee and got the lower price on the spot. Thirty seconds, thirty dollars. |
|
|
|
|
| Ask Jean |
 |
| Q: |
Today’s question comes from Andrea. She writes: "I opened a Trump account for my son, and he received the $250 contribution from the Dell family. Do I have to do anything to invest it, or is that done automatically?" |
| A: |
Quick refresher: Trump Accounts (officially 530A accounts) are the new, child-focused investment accounts created under recent legislation, which launched this summer. Contributions go into low-cost index funds and ETFs tracking the broad U.S. market. At 18, the funds transfer to the child to use as they choose – education, a car, a down payment, etc.
Earlier this year, Michael and Susan Dell pledged $6.25 billion to fund $250 deposits for 25 million American kids in lower-income ZIP codes through the Trump Accounts program. If your child is 10 or under and lives in a ZIP code with a median family income under $150,000, they will qualify. You can check eligibility here.
Now, as for what to do with the money once it’s in the account – whether it’s the $250 Dell contribution, the $1,000 newborns will get, employer contributions, etc. – you don’t have to lift a finger if you don’t want to. Funds default into the State Street SPDR Portfolio S&P 500 ETF (SPYM), a low-cost ETF tracking the S&P 500. According to the U.S. Treasury, it was chosen to provide "broad exposure to the U.S. stock market while maintaining expenses well below the statutory fee limitation."
Treasury has also selected four other low-cost index ETFs for the Trump Accounts investment lineup and plans to let parents choose how to allocate across them in the coming months. Until then, everything stays in the default fund. |
|
| Submit your questions to Jean here. |
|
|
|
|
|
|
|
| We maintain a strict editorial policy and a judgment-free zone for our community. We strive to remain transparent in everything we do. Website posts and newsletters may contain advertisements, links and mentions of products from our partners. Learn more about how we make money. |
| *This is a sponsored post |
|


