| Subscribe Read in Browser |
 |
| Today's newsletter is sponsored by |
 |
|
|
|
|
|
|
| This Week In Your Wallet |
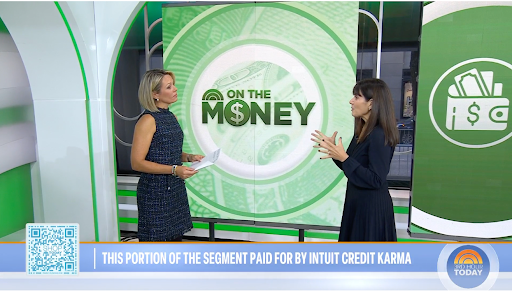 |
We’re in the "ber months," which means holiday shopping is right around the corner. And while it can be the most wonderful time of the year – it’s also often the most expensive, not to mention stressful. HerMoney CEO Jean Chatzky stopped by TODAY with budgeting and saving tips, starting with setting a limit: keep holiday spending to around 1% to 1.5% of your gross (pre-tax) income. "A good way to get ahead of it is to set your total holiday spending limit now," says Jean. "Look at what you spent last year if you need a starting point, then divide that number by the number of pay periods you have between now and the holidays." Most of us will have five, so do the math and move that amount into savings every payday. Then, you’ll have a dedicated holiday fund ready to go. For more of Jean’s advice, including how to consolidate your gift list and save on holiday travel, watch the full segment.
An inflation-proof retirement budget sounds too good to be true. But Wall Street Journal columnists Stephen and Karen Kreider Yoder say they've kept rising prices in check by spending something retirement gives you plenty of: time. That means taking the bus instead of a faster Uber, shopping around for better grocery prices, and cooking at home. Karen says a walk down a nearby street was her reality check. "At a cafe, I found a coffee for $7, a pastry for $8.50. At a boutique, a notecard was $7. A bowl of noodles nearby, $15," she writes. "I went home empty-handed. I can make coffee. I bake my own pastries. I create my own notecards. Retirement has put me in a world where life doesn't demand my buying as many things anymore, and where time can replace money."
Let’s hear it for the "girl dad" bosses. A paper in the Review of Economic Studies found one thing that changes how male managers treat women at work: having a daughter. Researchers at Northwestern University used administrative records to track every worker and company in Denmark from 1992 to 2017. They found that when male managers had their first daughters, the gender pay gap at the firms narrowed. "When a male manager had a first-born daughter, women’s earnings ratio – a measure of their pay relative to men’s – rose by 4.1%," The Economist reports. "The share of women employed at the company rose by 4.5%. The shift started immediately after the birth and lasted as long as the manager stayed at the firm. Having a son made no real difference, nor did subsequent daughters." |
|
|
|
| Things That Make You Money |
|
|
|
|
|
| The World Was Designed For Men – And It’s Costing You |
 |
From cars to sneakers, so much of our world was designed with men in mind. And not only is it inconvenient, but it also comes at a real cost to women.
So, in a world where women control over 80% of purchases, how did we even get here? And what is it actually going to take to change it?
Karen Reuther, author of Man-Made: How We Designed a World That Leaves Women Out, and How We Can Make It Right, joined Jean on the HerMoney Podcast to explain why, and what it would take to fix things.
As Reuther explains, the cost isn’t only what you pay at the register. It also shows up in your mental bandwidth. She pointed to her own commute from her home in Boston to Harvard’s Graduate School of Design, where she teaches. "I oftentimes will need to give much forethought to how I’m going to get there. I want to avoid certain subway stops because they don’t feel as safe to me. I even will avoid Harvard Yard in the winter and during the dark months because it’s very, very dark. So I spend an additional 10, 15 minutes each way to make sure that I’m walking a safe, lit, occupied path to and from."
That calculation, she said, is a tax most men never have to pay. "There’s this time — I call it the headspace gap — that we spend trying to plan out our journey, and cities are a really good example of that."
Jean connects the dots back to money. "If women are deciding they’re going to stay on the outskirts and not come into the city, we may be ignoring or bypassing some opportunities to earn more money if that’s where the money is," she said.
For more – including how to fight back with your own wallet – head here. |
|
|
|
|
|
|
|
|
| Ask Jean |
 |
| Q: |
Today’s question comes from Kym. She writes: "When calculating my net worth, do I include my HSA?" |
| A: |
Yes, when you calculate your net worth, you should include your Health Savings Account (HSA) balance.
Quick refresher: Your net worth is your real, overall financial position. It’s the bottom-line sum when you add up what you owe and subtract it from what you own.
Your HSA is an asset, so it belongs on the "assets" side of your net worth calculation. Keep in mind, though, if it’s earmarked for regular health costs, it’s not as flexible as cash in a savings account. That said, many people use HSAs as a retirement savings tool. If that’s you, include it in your net worth and also check in on it regularly to make sure it’s working as hard as possible in your retirement plan. |
|
| Submit your questions to Jean here. |
|
|
|
|
|
|
|
| We maintain a strict editorial policy and a judgment-free zone for our community. We strive to remain transparent in everything we do. Website posts and newsletters may contain advertisements, links and mentions of products from our partners. Learn more about how we make money. |
| *This is a sponsored post |
|