| Subscribe Read in Browser |
 |
| Today's newsletter is sponsored by |
 |
|
|
| Stat Of The Day |
| 62% |
| What’s mine…might not be yours. Data from Bankrate shows that most couples in committed relationships – 62% – keep at least some financial accounts in their name only. |
|
|
|
| Dr. Jill Biden On Money, Independence And Resilience |
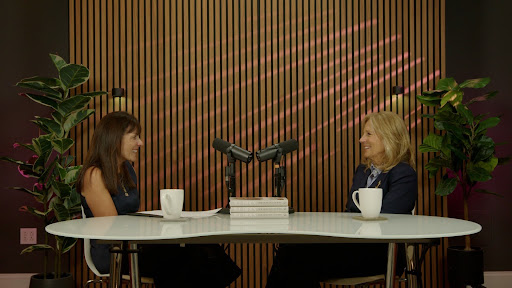 |
And you can count Dr. Jill Biden in that 62%. In her new memoir, View From The East Wing, Dr. Biden writes about losing her son Beau to brain cancer, nearly losing Hunter to addiction, and standing by President Joe Biden through his prostate cancer diagnosis. Through it all, she kept teaching community college English, making her the only First Lady in history to hold an outside job while her husband was in office.
On the HerMoney Podcast, Dr. Biden and Jean got candid about money, independence, and resilience. Her foundation of financial independence came from her mother, who told her: "You always have to have your own money." It's advice she passes on to every young woman she meets.
Dr. Biden’s family didn't have much growing up. Her father was a bank teller, and she and her three sisters shared a bedroom. But she never felt deprived. "We had butter and sugar sandwiches, but we loved butter and sugar sandwiches," she said. "We were so happy and never thought, 'Oh, she has this, and we don't.' We never, ever felt that way."
Those lean years left her with a saver's instinct and a Christmas Club account she still keeps to this day. Listen to the full episode here. |
|
|
|
|
| This Week In Your Wallet |
 |
Losing your job is hard. Losing it at 60 is a whole different beast – you’re close to retirement and many employers won’t bet on a short-term hire. "They may find themselves trapped between being too old to hire and too young to retire," says Catherine Collinson, CEO of the Transamerica Institute, whose recent survey found employers consider 65 "too old" to hire. USA Today talked to Americans laid off around age 60, including Cynthia Hennessy, who lost her corporate lawyer job at 61. She had low points – including being rejected for the Oscar Mayer Wienermobile – but landed at the Make-A-Wish Foundation of America. The pay is lower, but she's not complaining. "It's less responsibility," she says. "It's super-interesting, but I'm also only working 8 to 5, and I don't work on weekends." Three cheers to that.
Losing a job later in life can come with another gut-punch, too: having to figure out health insurance. As The New York Times reports, about 60% of people younger than 65 get their health insurance through their employer – but if you’re laid off, that coverage goes poof. While they can get insurance when they land a new job, older workers usually remain unemployed much longer than their younger counterparts. If you’re an older worker who is laid off, there are two moves to make immediately: First, ask HR whether your coverage ends on your last day or runs through the month. Second, if you're married (or in some cases, in a domestic partnership) to someone with workplace coverage, see if you can jump onto their plan. It's often your cheapest bridge to Medicare. Here’s the full rundown of your options.
Feel like dinner is eating up more of your day? You’re not imagining it. Federal data shows Americans now spend an average of 43 minutes a day on food prep and cleanup, up 34% since the early 2000s. "Schedules are more chaotic than ever. Dietary restrictions and picky eaters mean cooking multiple dishes," reports The Wall Street Journal. "The cost is growing, and so is the pressure to measure up to social media's army of food influencers." Food brands are eager to sell you convenience, but it comes at a cost. Grocery prices in July were roughly 26% higher than five years ago, according to the Labor Department, and some shoppers call the cost of premade meals "astronomical."
🍳 What's your go-to ingredient for saving time (and money) in the kitchen? Hit reply and tell us. We'll feature the best tips in a future newsletter! |
|
|
|
| Things That Save You Money |
|
|
|
|
|
| Ask Jean |
 |
| Q: |
Today’s question comes from Danielle. She writes: "If my husband and I get divorced, what happens with his Social Security benefits? Do I lose my stake in those?" |
| A: |
Short answer? No, not necessarily. If you were married for at least 10 years, you're currently unmarried, and you're 62 or older, you may be able to collect a benefit based on your ex's work record.
A few conditions to know: your ex must be at least 62 and eligible for retirement benefits. If you've been divorced for at least two years, he doesn't need to have filed yet. The benefit can be up to 50% of his full retirement age amount (less if you claim early), and it only helps if that's more than your own benefit. Social Security looks at your own benefit first and then, if his spousal amount is higher, you get the difference added on.
If you remarry, you generally can't collect on your ex's record anymore (the exceptions are very limited). If that marriage ends, you may be able to claim on a prior ex's record again, as long as that marriage lasted over 10 years.
The bottom line here is that divorce and remarriage both change your Social Security math. When in doubt, contact the Social Security Administration directly to confirm your specific situation. |
|
| Submit your questions to Jean here. |
|
|
|
|
|
|
|
| We maintain a strict editorial policy and a judgment-free zone for our community. We strive to remain transparent in everything we do. Website posts and newsletters may contain advertisements, links and mentions of products from our partners. Learn more about how we make money. |
| *This is a sponsored post |
|


