| Subscribe Read in Browser |
 |
| Today's newsletter is sponsored by |
 |
|
|
| Stat Of The Day |
| 45% |
That’s how much lower the median 401(k) balance is for student loan borrowers in their 40s than those without student loan debt, according to new research.
If you’re still paying down student loans, it’s worth checking into whether your employer matches student loan payments with retirement contributions. Some do, thanks to SECURE 2.0. |
|
|
|
| This Week In Your Wallet |
 |
Looking for love – or a stronger connection with your partner or a friend? Head to one of our favorite retailers. As USA Today reports, beyond shopping for rotisserie chickens, a year’s supply of paper towels, or the infamous hot dog combo, more and more people are deepening their relationships in Costco aisles. "On the surface, Costco is a popular spot for Americans to stretch their grocery dollar, but it also feeds a deeply human need. As physical community spaces disappear and social bonds fray, the warehouse giant has emerged as an unexpected anchor for connection," reports USA Today. And the timing couldn’t be better. Federal data shows face-to-face socializing is on the decline, with Americans spending only 35 minutes a day connecting in person, down 15% from a decade ago.
It’s almost spooky season – and the scariest thing you encounter might not be the price of a pumpkin spice latte. It’s the "ghost charges" on your credit card. As Michelle Singletary writes for The Washington Post, these are the charges we forget about or consciously ignore: the streaming subscription we never use, the food delivery we order on the regular, etc. "Frictionless transactions – including one-click pay, tap to pay, mobile payment apps and saved autofill credit card prompts – have made buying so effortless that in many instances we don't feel the psychological pain of paying," Singletary writes. Her fix? Print out your statements and scrutinize every charge. "I don't want you to rely on your banking app to check your numbers. These dashboards sort your spending into tidy graphs that make it feel like it's under control," she writes. "But a pie chart showing $400 in food spending doesn't tell the full story. In reality, spending $60 on a McDonald's delivery undercuts what you say is your goal to pay down debt or save more."
Bond yields recently hit their highest level in two decades. As this piece from The Wall Street Journal explains, now is a good time to buy – and think about rebalancing your portfolio. Economic indicators suggest stocks are pricey, with valuations near dot-com-bubble highs, pointing to lower returns over the next decade. Meanwhile, high-quality bonds are offering unusually attractive yields. Tax-exempt municipal bonds from high-tax states are paying around 5%, and 20-year Treasury Inflation-Protected Securities (TIPS) offer about 3% plus inflation protection. "Now is a good time for investors to examine their portfolios to determine whether rebalancing the mix of assets is appropriate," writes the legendary economist Burton Malkiel. "Investors near or in retirement should consider increasing their allocation to bonds." |
|
|
|
 |
| Not sure where to start? Our partner Willow can help. Rebalancing is easier with a second set of eyes. Willow matches you with a financial advisor based on your goals and situation, so you're not going it alone. Take this two-minute quiz to get started. |
|
|
|
| Things That Make You Money |
|
|
|
|
|
| The Secret To Building Wealth As A Normal Person |
 |
In 1971, about 61% of U.S. households were middle class. Today, that number is closer to half, with households being pushed toward both ends of the income spectrum for 50 years straight. But no matter where you land on that K-shaped economy, most of us still think of ourselves as just regular people trying to get by (and hopefully retire someday).
On a recent episode of the HerMoney Podcast, Jean Chatzky talked wealth-building for the middle class with Joel Larsgaard, co-host of the How To Money podcast. He doesn't sugarcoat the headwinds – but he's genuinely optimistic about middle-class people building wealth.
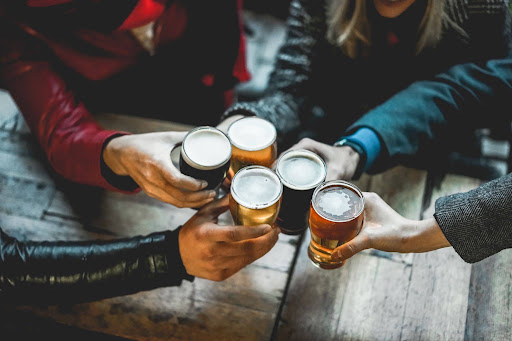
Larsgaard says it starts with spending smarter. His trick? Finding your "craft beer equivalent" – the handful of things worth paying up for, guilt-free, so you can cut back everywhere else.
"There are certain things in life that are worth spending lots of money on," he explained. "If you pick just a handful of things that you say, 'No matter what's going on, this is going in my budget, and I'm super stoked to spend money on it'… that actually provides a lot of satisfaction for people and more of an ability to cut back in other places where they've identified that's not as big of a priority."
For Larsgaard, that list has evolved – these days, what he's really buying is time. "I'm coaching my daughter's middle school cross country team right now, because I've created this lifestyle where I can focus on that more than on buying more things or a bigger house or a nicer, newer car." |
|
|
|
|
| Ask Jean |
 |
| Q: |
Today’s question comes from Judy. She writes: "How soon before I turn 65 should I be thinking about my Medicare decisions?" |
| A: |
Honestly? Probably a lot earlier than you might think. With so many things to consider – including whether to go the Medicare Advantage route or opt for traditional Medicare – it’s important to start thinking about your healthcare options sooner rather than later. Rushing the decision is how people can end up with coverage that doesn’t fit their needs.
As you may already know, your "Initial Enrollment Period" is a seven-month window that opens three months before the month you turn 65 and closes three months after it. Experts say the time to really start digging in is six months before your birthday, which is before the window even opens. "We always tell everybody, start as soon as you’re able to," stresses Diane Omdahl, Medicare expert and co-founder of 65 Incorporated. "And that means that before your initial enrollment period starts, you need to begin your preparation and your homework so that you can make your own smart decisions."
That homework that Omdahl mentions should include: |
|
| ● |
Making a list of your doctors and prescriptions |
| ● |
Comparing Original Medicare and Medicare Advantage side by side |
| ● |
Putting your enrollment window's open and close dates on your calendar so you don’t miss them (or you could face late enrollment penalties) |
|
| One other thing to add to your list: Listen to this episode of the HerMoney Podcast, where we dig into all things Medicare with Omdahl and her 65 Incorporated founder (and daughter!), Melinda Caughill. It’s packed with useful information. |
| Submit your questions to Jean here. |
|
|
|
|
|
|
|
| We maintain a strict editorial policy and a judgment-free zone for our community. We strive to remain transparent in everything we do. Website posts and newsletters may contain advertisements, links and mentions of products from our partners. Learn more about how we make money. |
| *This is a sponsored post |
|


